
Making a Difference
How UN training is reshaping rural savings clubs run by Afghan women
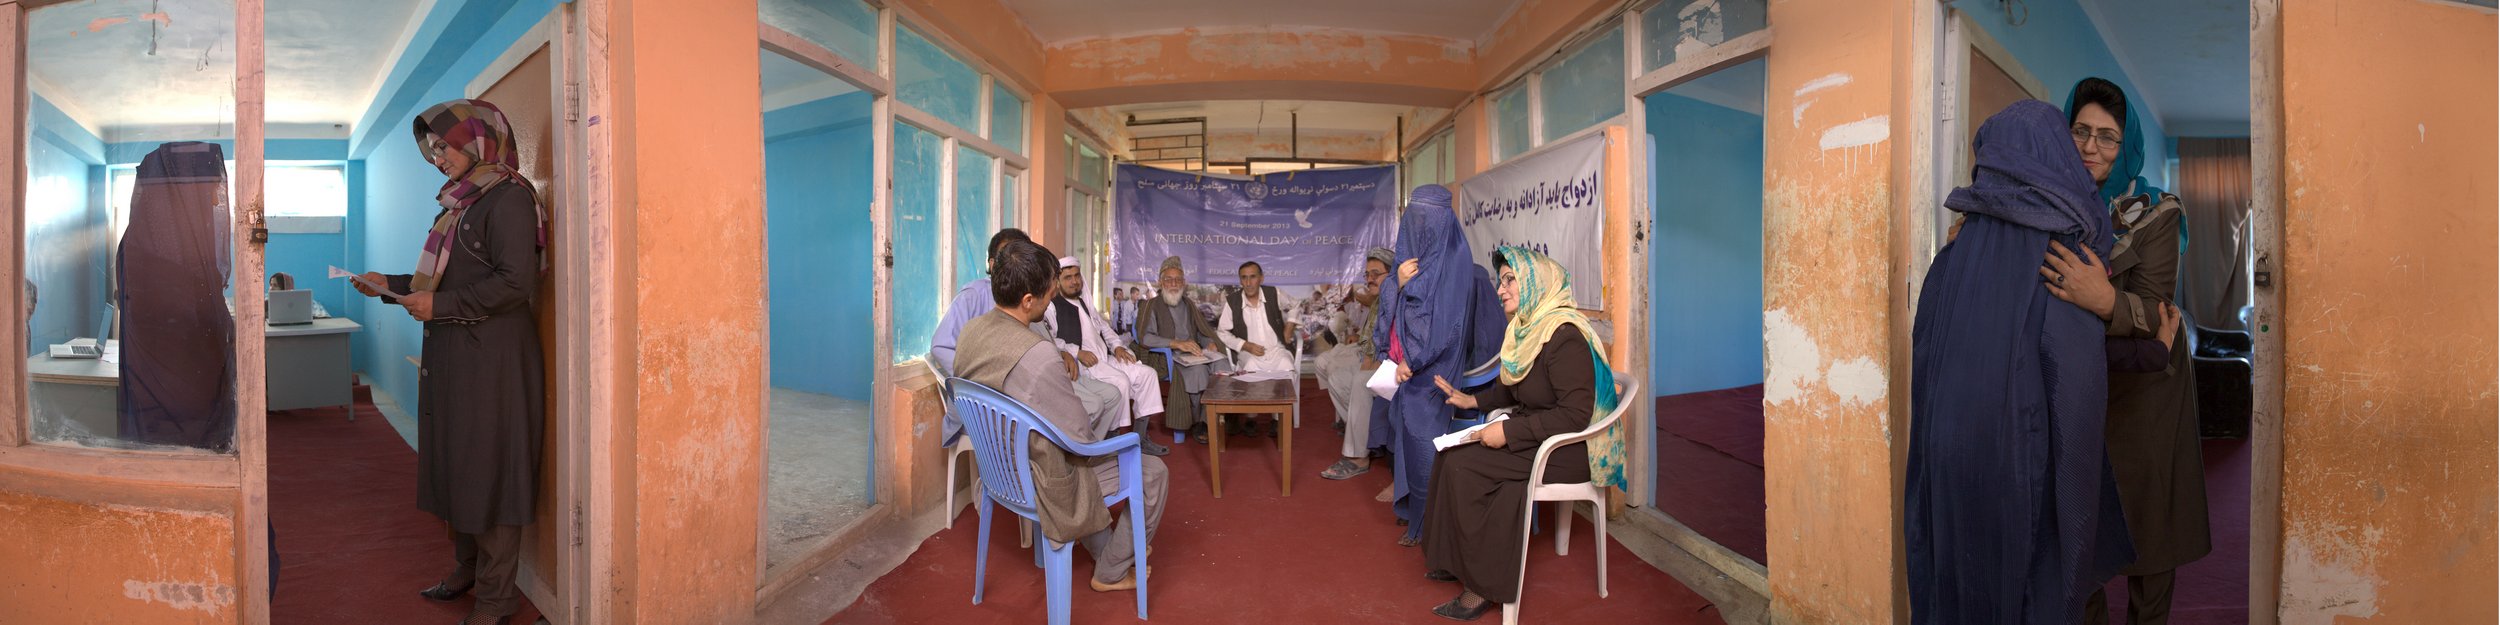
In a small village outside Herat, a group of women gather every Saturday under a mulberry tree with a hard-cover ledger, a pencil, and the practiced confidence of bookkeepers. They are part of a quiet movement: rural savings clubs across Afghanistan whose members have been trained by United Nations programmes to keep group accounts themselves, in their own hands, in their own handwriting.
These clubs did not emerge from a single policy document. They grew from a recognition that formal banking rarely reaches the women who grow wheat, tend goats, and raise children in districts far from the provincial capital. By teaching basic record keeping, cash handling, and group governance, UN agencies have helped thousands of women take the first steps into a financial life their mothers were not permitted to imagine.
The same instinct that drives a community-organised punting syndicate at Flemington, or a Saturday morning coaching fund at a suburban Brisbane oval, is at work in these villages: people pooling small amounts, trusting one another, and recording every cent. The tools differ, but the discipline of transparent bookkeeping is shared.
This article looks at how the training was designed, what daily account keeping actually involves, the measurable outcomes for women and their families, and what Australian readers and institutions can recognise in their own backyards.
Where the rural savings club idea came from
The model has deep roots. Microfinance experiments in Bangladesh and Bolivia in the 1980s and 1990s showed that very small loans, given to groups rather than individuals, could reach people the formal banking system had ignored. United Nations agencies working in Afghanistan after 2002 studied these approaches and asked a different question: what if, instead of starting with lending, the programme started with saving?
Saving came first because it asked nothing of a husband, a father, or a village elder. A woman could set aside a handful of afghanis from the sale of eggs, wool, or surplus vegetables without needing permission to take on debt. Once the group had a small pool of capital, the same UN trainers introduced credit, then small business support.
The cultural fit mattered as much as the financial design. Afghanistan's rural districts are overwhelmingly conservative, and women's public lives are tightly constrained. The UN worked through existing women's shuras, religious networks, and health committees, training local facilitators who could deliver lessons in Dari and Pashto without offending local norms. The result was a programme that looked less like a foreign bank and more like a village tradition with a ledger.
Inside the UN training curriculum
The training is deliberately simple. A typical cycle runs for six to eight weeks, with sessions of about two hours held in a community room, a health clinic, or a private home. Trainers use laminated flashcards, an exercise book for each participant, and a single shared ledger that stays with the elected treasurer of the club.
The curriculum covers four skills. Basic numeracy and money recognition, since many members have never handled banknotes larger than the smallest denominations. The discipline of the cash box: counting cash in front of at least two witnesses, locking the box with two keys held by different people, and recording every withdrawal in coloured ink. Double-entry bookkeeping adapted for low literacy, using pictures, stamps, and tick marks. Group governance: electing officers, setting meeting times, and managing disagreements without outside arbitration.
Graduation is the moment the trained group opens its first savings cycle, accepts contributions from every member, and balances the books at the end of the first month without help from the trainer. The UN team then steps back to a supervisory role, visiting quarterly, reviewing the ledger, and connecting successful clubs to formal banks, mobile money operators, or cooperatives.
A Saturday morning in a Herat savings club
By eight o'clock the treasurer arrives with the locked cash box, the cloth-wrapped ledger, and a small wooden stamp she carved herself. Members drift in through the side gate in twos and threes, some still wearing the shawls they walked the fields in, others carrying toddlers who will spend the meeting playing under the apricot tree.
The meeting follows a familiar rhythm. The secretary reads the previous week's balance. Each member announces her deposit, hands over the cash, and watches as the treasurer writes the amount in the passbook. Loan repayments are recorded in red ink, new deposits in blue, penalties in a third colour. Loans, when the pool allows, are proposed by members, seconded by another, and approved by a show of hands.
Before the box is locked again, two members count the cash aloud. The treasurer and secretary both sign the reconciliation page. If the numbers match, the meeting closes with a short prayer, green tea, and a reminder of the next session. The process rarely takes more than an hour, but the discipline is fierce: a club in Badghis that lost thirty thousand afghanis to a treasurer who kept the books alone taught every neighbouring district what careful recording looks like.
| Feature | Afghan rural savings club | Australian community credit union | Informal rotating savings group |
|---|---|---|---|
| Governance | Elected committee of three to five members, trained by UN facilitators | Board elected by members, regulated by ASIC and APRA | One trusted convenor, often a family member or friend |
| Record keeping | Paper ledger, handwritten, double-entry adapted for low literacy | Digital core banking platform, regulated ePayments Code | Notebook or memory, sometimes a group chat thread |
| Typical membership | 15 to 30 women from one or two nearby villages | Hundreds to tens of thousands across a region | Five to twenty people, often kin-based |
| Returns on savings | Small annual share-out of profits, no interest on deposits | Regulated interest, depositor protection | None: each person takes the pool once, in turn |
| Legal status | Informal, not registered as a financial institution | Registered co-operative or mutual bank | Informal, outside the National Consumer Credit Protection Act |
Comparing the Afghan model with other approaches
The Afghan club is not the only model of community finance. In Kenya, informal savings groups known as chamas often invest in property, school fees, and small businesses, but rarely keep the detailed ledger that allows an outsider to audit the books. In Bolivia and Colombia, community banks have decades of experience with full double-entry bookkeeping, but usually operate in urban settings where literacy is universal.
What the Afghan programme has done is combine the inclusivity of a chama with the rigour of a Latin American community bank, in a context where most members have never used a calculator. Materials are designed to work for women who may not read fluently, using symbols, colours, and physical tokens to stand in for numbers.
Technology is beginning to change the picture. Some clubs now record transactions on a basic smartphone, photograph the paper ledger, and share the image with a UN supervisor. Similar tools are used by regional partners working with displaced women in the Western Balkans. Digital tools work best when they sit on top of strong paper habits, not in place of them.
What changes for the women and their families
Evaluations of UN-supported programmes in Afghanistan show measurable shifts in how women manage household money. Members report being more likely to decide jointly with their husbands how savings are spent, to keep cash aside for medical emergencies, and to send daughters to school for longer. The numbers are small, often a few percentage points, but they move in the same direction across dozens of districts.
The social effects are harder to count. A woman who has balanced a ledger in front of her neighbours is harder to dismiss at home. She has a recognised role, a public skill, and a network of peers who will back her if a husband or father-in-law challenges her right to save. Several clubs have gone on to negotiate directly with local traders for fairer prices on embroidery, nuts, and pomegranates, using the group's collective weight where a single woman would have been ignored.
The limits are real. In more conservative districts, members still need a male relative's permission to attend meetings, and a few programmes have faced pushback from commanders suspicious of organised female activity. Drought, displacement, and insecurity can wipe out a season's savings in a single failed harvest. The training does not solve these problems, but it gives women a tool to absorb small shocks and rebuild quickly.
What Australian readers can recognise at home
Australia has its own long tradition of community-owned banking, from the mutual societies of nineteenth-century Melbourne to the Bendigo Bank branches that still serve towns like Castlemaine and Inverell. The same instinct that keeps a regional credit union alive in a wheat-belt town is the instinct that keeps a savings club alive in a Daikundi village. The legal frameworks are different, but the discipline of transparent books, elected officers, and shared ownership is familiar.
For the roughly fifty thousand people of Afghan background in Australia, particularly in south-western Sydney and Melbourne's northern suburbs, these programmes are not abstract. Many arrived as refugees and continue to send remittances home through informal networks built on the trust principles the UN is now codifying. Australian community organisations are partnering with savings groups in both countries, recognising that the bookkeeping habits trained in a Herat ledger are the same habits that help a Hazara family in Auburn balance a household budget.
Australian regulators have something to offer. The ePayments Code, the Banking Code of Practice, and ASIC's guidance on mutuals set a high bar for record keeping and member protection. None of these tools transplant wholesale into a rural Afghan context, but their principles can. Transparent books, two-key cash controls, and elected oversight are universal safeguards that work as well under a mulberry tree as in a boardroom in Sydney.
Practical steps to strengthen community savings
The Afghan experience offers a handful of practical lessons drawn from the training manuals used in UN-supported programmes and from the feedback of club members in seven provinces.
- Begin with savings, not loans. A shared pool of deposits gives a group skin in the game and a reason to keep careful records.
- Train at least two officers in every club, and rotate the treasurer role yearly. Concentrating the books in one pair of hands is the most common cause of fraud.
- Design the ledger for low literacy, not for accountants. Use coloured ink for different transaction types and symbols for loan categories.
- Reconcile the cash box in public, every meeting, with at least two members counting aloud.
- Connect every club to a supervising body that visits quarterly, reviews the ledger, and signs the minutes.
- Introduce any digital tool only after paper habits are strong. A smartphone photograph of a well-kept ledger is powerful evidence; a photograph of a mess is not.
- Treat the group ledger as a legal document, not a personal notebook. The record belongs to the group, not the treasurer.
The work continues. Displacement and economic stress push Afghan families into situations where a handful of saved afghanis can mean a child going to school instead of to work. The UN's broader effort, including legal documentation support for displaced families, depends on the same careful paper trail a Saturday savings club keeps. Readers can explore the UN Afghanistan archive to follow these stories. Financial dignity, like good bookkeeping, is built one careful entry at a time.